
SIMPLIFYING LIFE AFTER WOR(K)What It's Actually Like to Work With Us
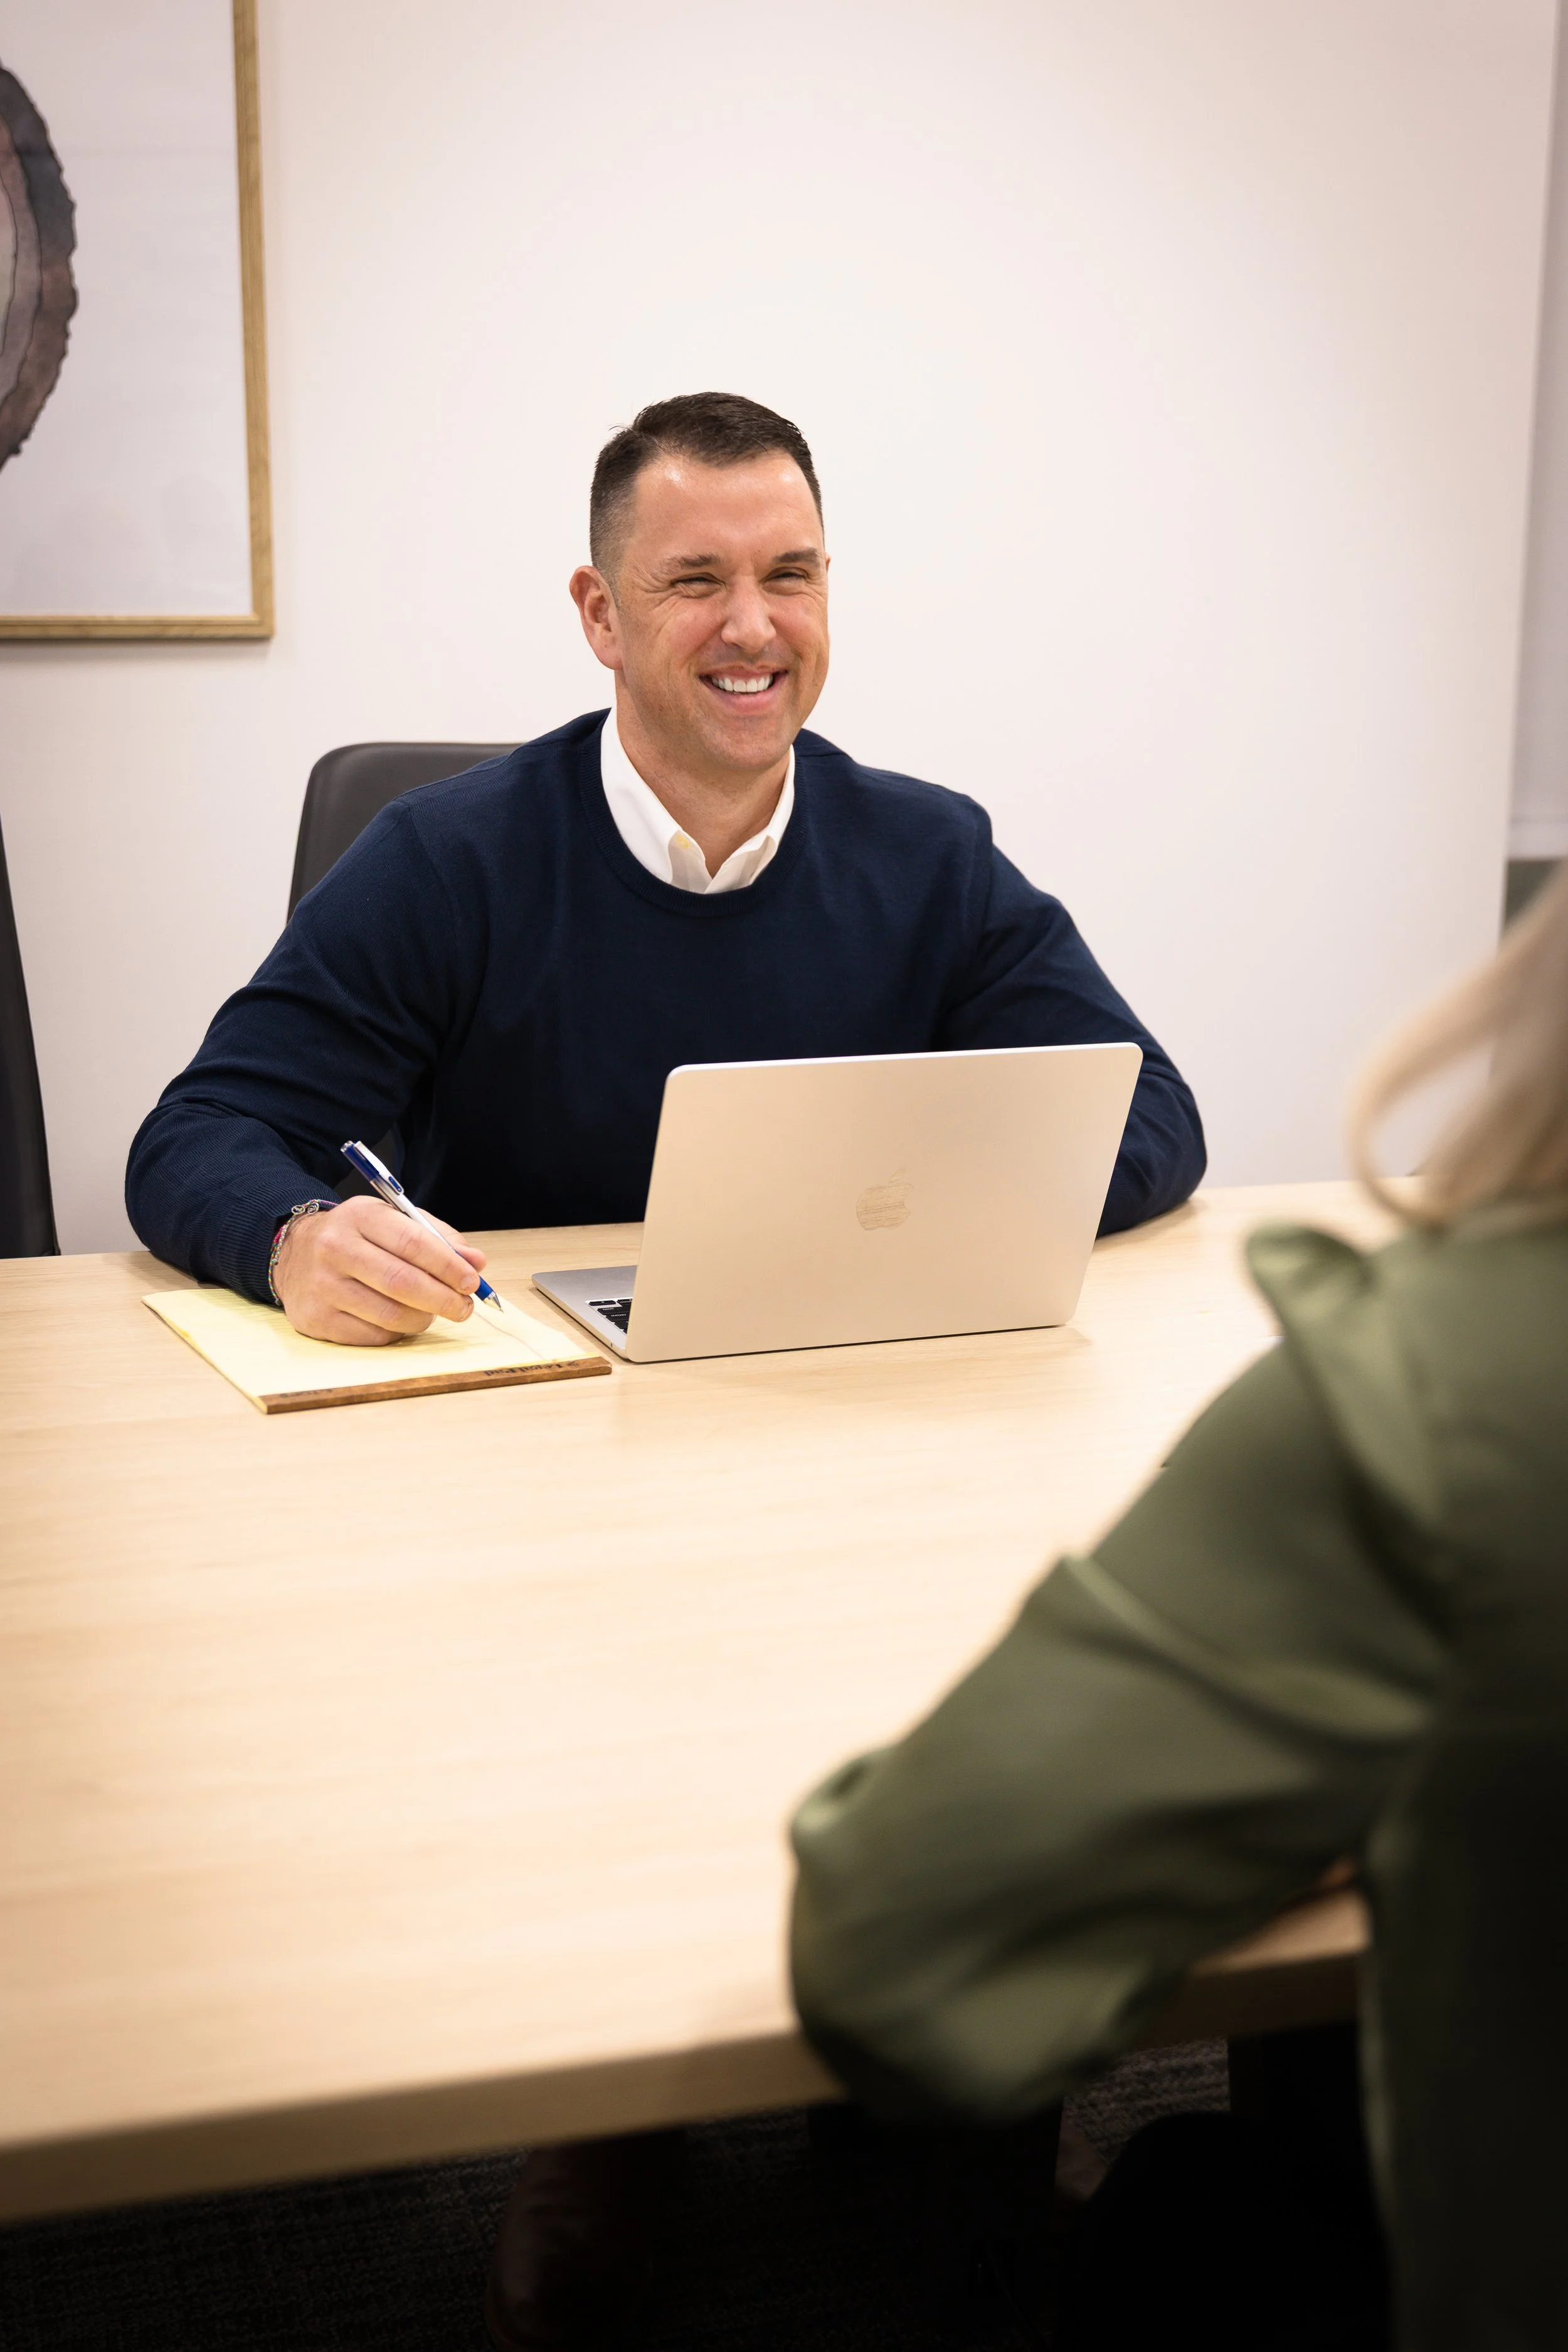
No mystery, no jargon, no wondering what happens next. Our process is built so you always know exactly what's happening, why it matters, and what's coming, from your first conversation through years of ongoing planning together.
HOW WE INVESTOur Investment Philosophy
Great investing isn't about predicting the next headline, and honestly, nobody can do that reliably. It's about building a consistent process you can actually stick with, through good markets and bad ones. Here's what we believe, and why.
Public Markets Are Mostly Efficient
Since public markets absorb new information quickly, consistent stock-picking or market timing is difficult, especially after taxes and costs. So we focus on what we can control: low costs, tax efficiency, and broad diversification.
Behavior Drives Returns
Long-term returns are driven by staying invested and avoiding emotional decisions during volatility. We see behavioral coaching as a core part of managing your portfolio, helping you stay focused on the plan rather than the headlines.
Private Markets as a Diversifier*
For the right investors, allocations to private equity, private credit, infrastructure, and real estate can enhance returns and add diversification. We treat private markets as a complement to a strong public market foundation, not a replacement for it.
In practice, this means your portfolio is built in layers: a diversified, low-cost, tax-aware core in public markets, thoughtful private market allocations where appropriate, and ongoing oversight that includes rebalancing, tax-aware strategy, and regular communication through every market cycle.
OUR SERVICE COMMITMENTAn Ongoing, Structured Planning Process
Investment & Estate Planning
We review and update your investment strategy, look at IRA and Roth IRA contribution or conversion opportunities, revisit your estate plan and beneficiary designations, and talk through charitable giving and legacy planning.
Tax Planning
We review your current-year tax liability, identify tax-loss or tax-gain harvesting opportunities, look at HSA, FSA, and 401(k) benefits, plan for upcoming education expenses and 529 contributions, and begin preparing for year-end tax moves.
Financial Plan & Mid-Year Review
A check-in covering cash flow, savings goals, and emergency funds, along with a review of your investment strategy and asset allocation, real estate or refinancing opportunities, and any other planning recommendations.
Year-End Review
A full portfolio and performance review, finalized year-end tax strategies and harvests, a refreshed financial plan for the year ahead, an insurance and risk check, and a look at debt, credit, and overall goal alignment heading into the new year.
How This Plays Out, By Planning Level
On a quarterly cadence, each of the four areas above gets its own dedicated meeting throughout the year. On a three-meeting cadence, these areas are consolidated into three sessions. On a two-meeting cadence, Investment & Estate Planning and the Financial Plan Review are typically covered together in the first half of the year, with Tax Planning and the Year-End Review covered together in the second half.
STEP BY STEPOur Process, Start to Finish
Our process is built so you always know what's happening, why it matters, and what comes next, from your first conversation through years of ongoing planning.

Introductory Meeting
Just a conversation, no pitch, no pressure. We want to understand your situation, your goals, and what you're actually looking for in an advisor, and you should walk away knowing whether we're a fit too.

Discovery & Data Gathering
We gather key financial information, including investments, taxes, equity compensation, estate documents, and insurance, to see the full picture.

Analysis & Planning
We analyze your full financial picture and identify the gaps, risks, and strategies that matter most to your long-term goals.

Plan Presentation
We walk you through our recommendations in plain language, no jargon, and explain the reasoning behind every one, so you know exactly what's next and why it's right for you.

Onboarding
If you move forward, we handle account setup, transfers, and connections to custodians and partners, along with access to your dashboard.

Ongoing Advice & Reviews
This is where the real relationship begins. Quarterly reviews, ongoing communication, and advice that keeps up with wherever life takes you next.
THE RELATIONSHIP BEGINS HERE“The plan is not the finish line. It is the framework for every decision that follows.”
WHAT CLIENTS ASKFrequently Asked Questions
-
How often you meet with your advisor depends on your financial planning level, two, three, or four times a year. Every level covers the same ground, investment strategy, estate planning, tax planning, and a year-end review, just paced differently depending on your cadence. Between meetings, we reach out proactively whenever timing matters and stay available for anything that comes up.
-
The first meeting is a free-flowing conversation focused on understanding your situation, your goals, and what you're looking for in an advisor, with no obligation or expectation to move forward.
-
We believe public markets are largely efficient, so we focus on diversification, minimizing fees and taxes, and staying disciplined around a long-term plan rather than trying to predict short-term market movement.
-
Our investment consultants add an extra layer of research and experience to our portfolio decisions, helping ensure they're evidence-based, consistent, and aligned with your long-term goals.
-
Investor behavior is one of the biggest drivers of long-term results. We help clients stay invested and avoid reacting to short-term market noise, since a good plan only works if you can stick with it.
-
For the right clients, exposure to private equity, private credit, infrastructure, and real estate can improve long-term returns and reduce volatility. We use these investments to complement a public market foundation, not replace it.
*Disclosure: Investments in private equity, private credit, real estate, infrastructure, and other alternative investments involve significant risks and are not suitable for all investors. These investments may be available only to investors who meet certain income and net worth qualifications (“accredited investors” or “qualified purchasers” as defined under federal securities laws). Risks include, but are not limited to: illiquidity and long lock-up periods (capital may be committed for 7–10+ years); higher fees and expenses than traditional investments; limited transparency and infrequent valuation; use of leverage that may amplify losses; limited or no secondary market; potential for total loss of invested capital; and valuations that may not reflect actual realizable value. Apparent reduction in volatility may result from infrequent pricing rather than genuine risk reduction. Diversification does not guarantee a profit or protect against loss. Past performance of alternative investments is not indicative of future results.
THE FIRST STEP IS SIMPLEReady to See This Process in Action?
Let's schedule an introductory conversation and see if we're the right fit.