
RETIREMENT PLANS FOR GROWING COMPANIES401(k) Plans That Actually Work for Your People
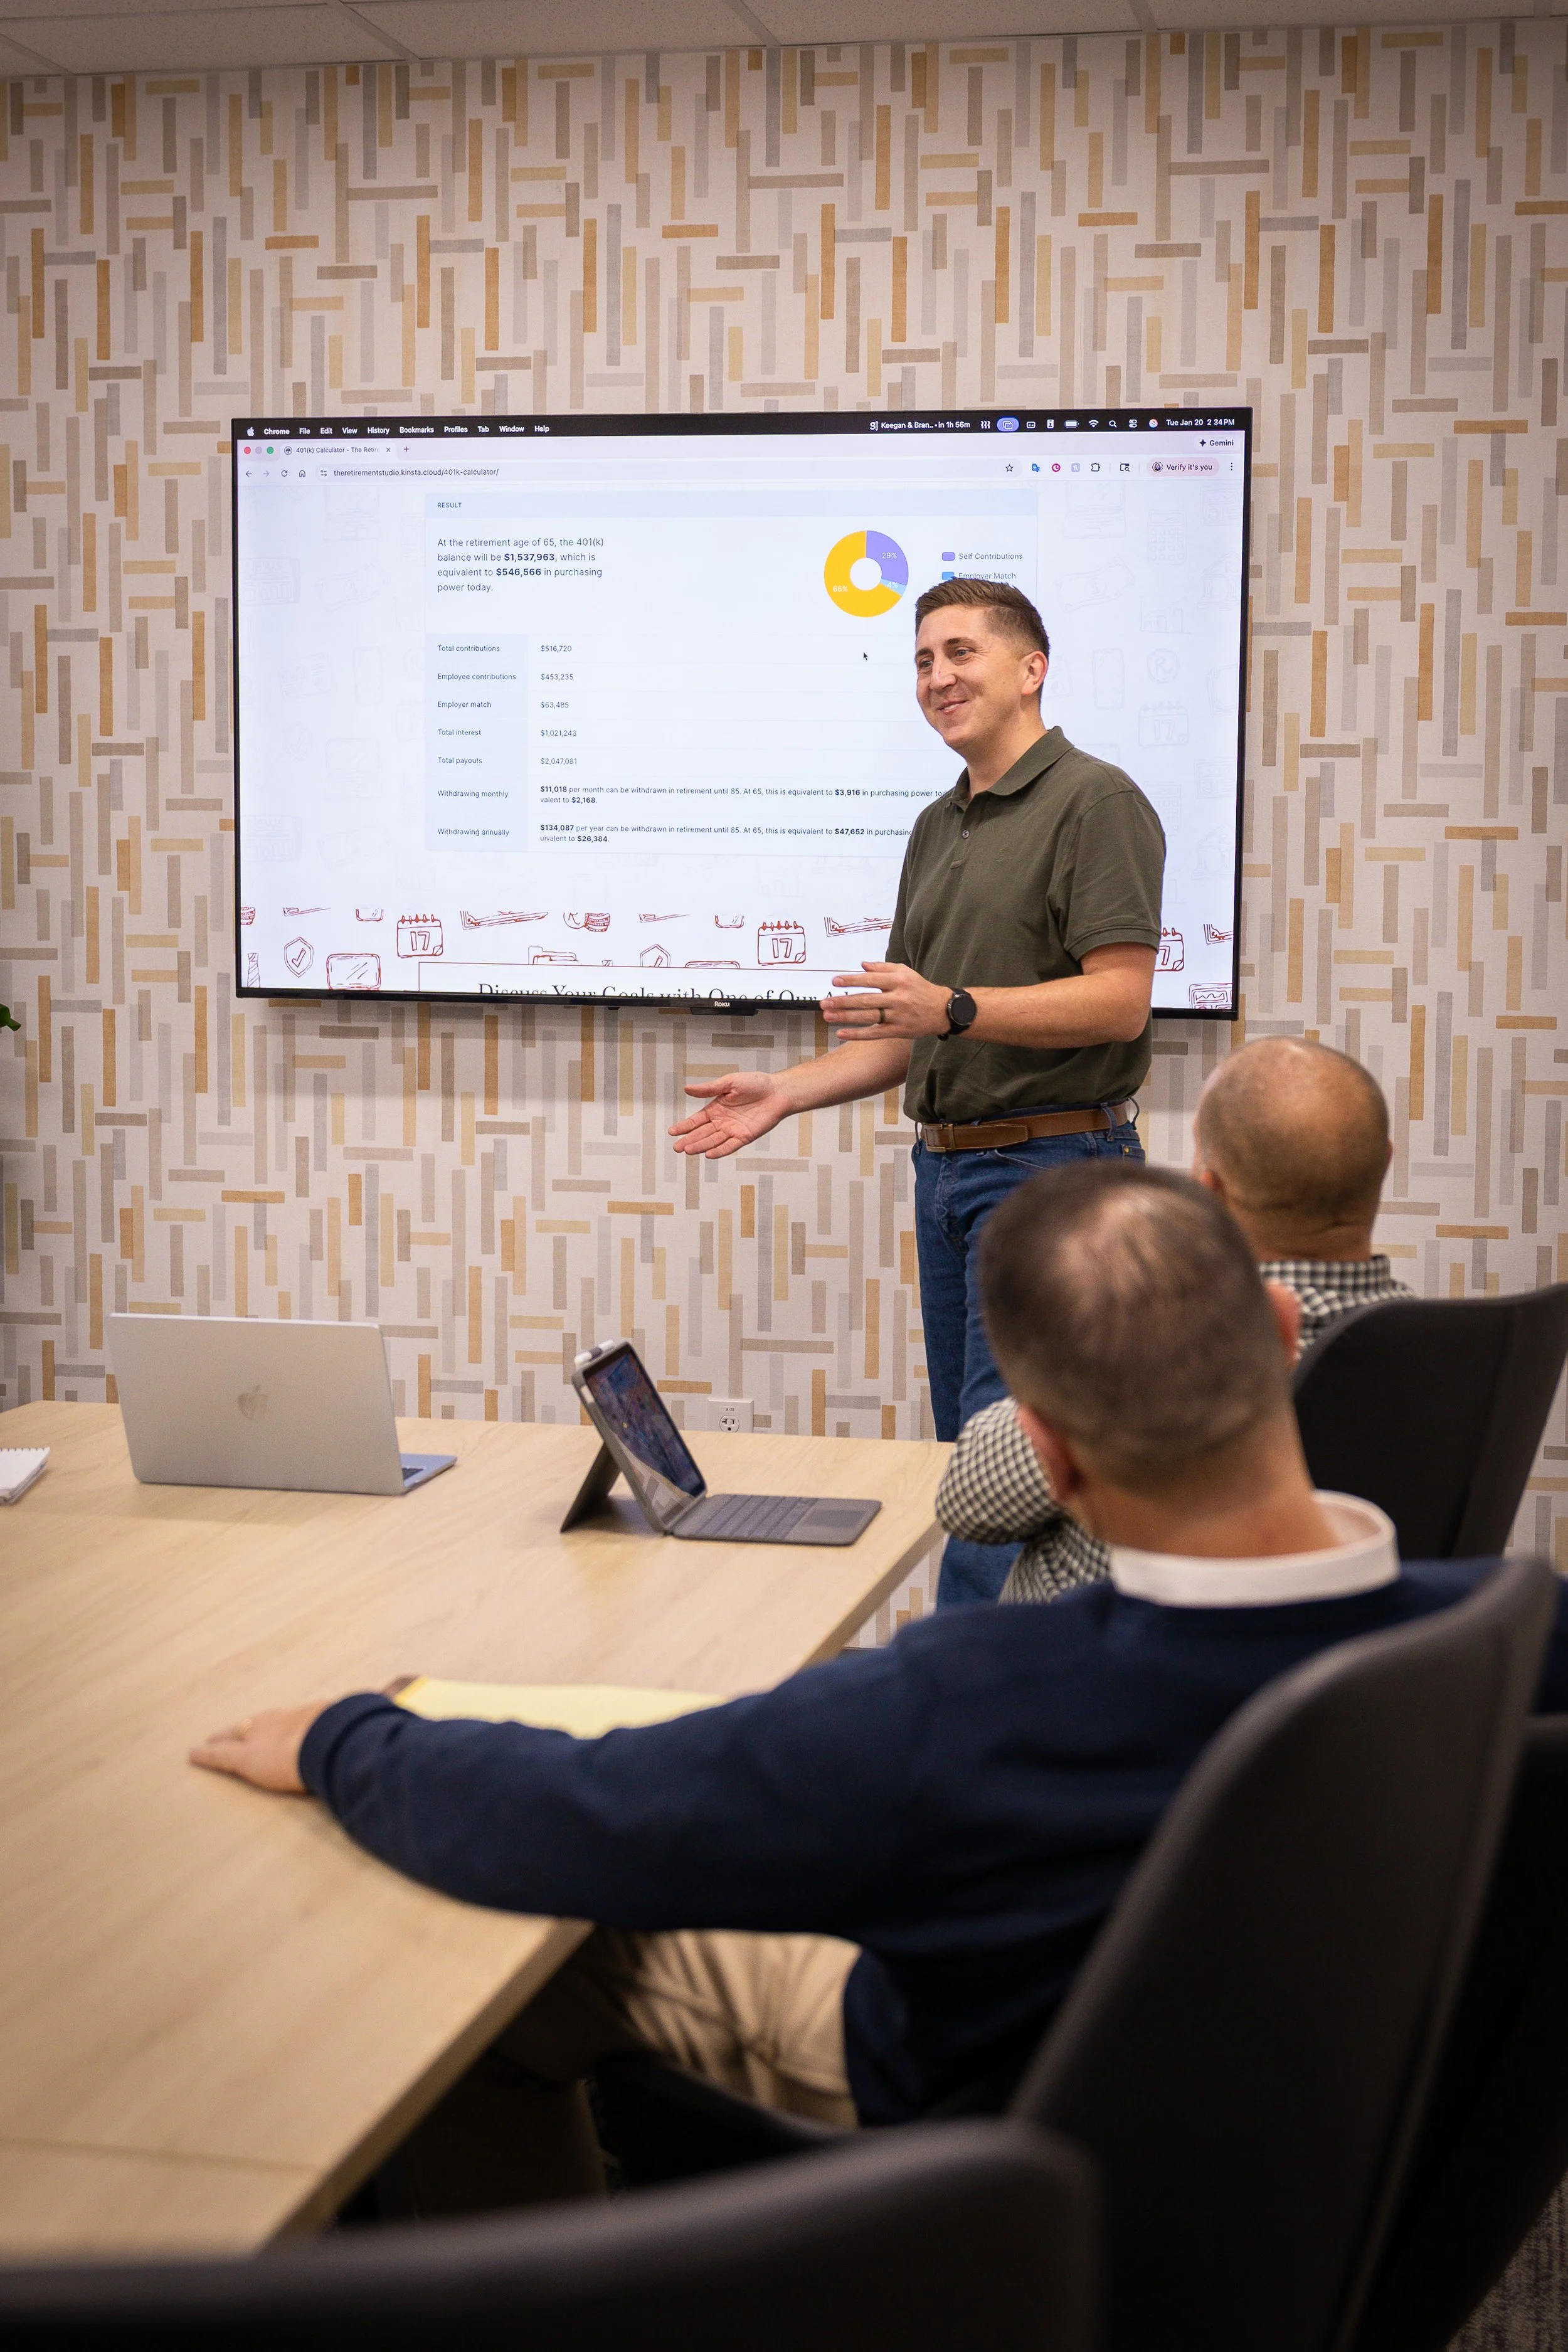
A retirement plan should feel like a benefit, not a compliance headache. We help growing companies build 401(k) plans that genuinely work for their employees and their business, with clear administration, tailored plan design, and a fiduciary standard you can rely on. It's part of how we simplify life after work, for the people running the business and the people working in it.
WHO WE HELPWho We Work With
Retirement plans are built for companies, but they succeed one person at a time. We design around both sides of that equation.
Business Owners
A strong retirement plan is one of the most effective tools you have for attracting and retaining talent in a competitive hiring market. We help you build a 401(k) that goes beyond the bare minimum, one that genuinely supports your employees' financial futures, without adding hours of administrative work to your week. From plan design to ongoing oversight, we handle the complexity so the benefit stays valuable to your team and simple for you.
HR & Finance Executives
You're often the one fielding employee questions, managing compliance deadlines, and coordinating with a provider that doesn't always make things easy. We act as an extension of your team, handling day-to-day plan administration, payroll coordination, and compliance testing, so retirement benefits are one less thing competing for your attention.
Companies
Every company's workforce and goals are different, which is why plan design shouldn't be one-size-fits-all. Whether you need a safe harbor design to simplify nondiscrimination testing, a profit-sharing structure to reward tenure and performance, or a cash balance plan for higher-earning owners and partners looking to accelerate retirement savings, we help you find the structure that actually fits your business.
A BETTER OPERATING PARTNERWhy Work With The Retirement Studio
We connect the provider, payroll, investments, compliance, and employee experience—so your plan works as one coordinated benefit.
Administrative Support
If you've ever spent an afternoon on hold with a record keeper, you already know why this matters. Our advisors act as the single point of contact between you and your 401(k) provider, managing that complexity directly so your internal team can reclaim the time it used to spend untangling plan logistics.
Tailored Plan Design & RFPs
The Department of Labor recommends benchmarking your plan's fees and services regularly, and we build that into our process by issuing a competitive RFP every three years. This gives you an objective look at whether your current fee structure, investment lineup, and provider services are still the best fit, and it gives you documentation showing you've fulfilled your fiduciary duty to monitor the plan.
Payroll Integration
Manual contribution submissions are a common source of errors and delays. We integrate directly with your existing payroll provider, so employee contributions, deferral changes, and loan repayments flow through accurately each pay period, one less thing on your plate.
FIRST WE TRY TO FIX ITPlans That Already Exist
Business owners usually call us for the same reason: something about the plan stopped working. Fees crept up with no explanation, testing failed again, deferrals get keyed by hand because payroll and the record keeper don't talk, and half the staff never enrolled.
Our industry's reflex is to switch providers. Sometimes that's right. Often it just trades one problem for a blackout period, new notices, and weeks of your HR team's time, when the real fix was already sitting inside the plan you have.
So we start there: the document, the fees, the fund lineup, the service agreements, how the plan actually runs day to day. Then we tell you what we found, and what we'd change, whether or not that means hiring us.
WHAT WE CAN FIX WITHOUT MOVING YOUR PLAN
ENGAGE YOUR EMPLOYEES
INTEGRATE PAYROLL
SET UP EDUCATION
CLEAN UP RED FLAGS
NEGOTIATE & REPRICE
ADJUST FUND LINEUP
ADD 3(16) FIDUCIARY SERVICES

THE 3(38) ADVANTAGEFiduciary Investment Management, Handled for You
As your plan's 3(38) investment manager, we take on the legal responsibility for selecting and monitoring your plan's investment options, a role most advisors don't hold. This shifts a significant portion of fiduciary liability away from you as the plan sponsor and onto us, while giving your employees a professionally managed lineup built with their outcomes in mind.

EMPLOYEE EDUCATIONHelping Your Employees Actually Use Their Benefits
A great plan only works if your employees understand it. We blend in-person sessions with technology-based education to reach both onsite and remote employees, so every member of your team feels confident about their retirement benefits, not just aware that they exist.
“88% consider their retirement plan one of the most important workplace benefits.”
SWITCHING IS SIMPLESwitch 401(k) Providers in Under 90 Days
Sometimes the honest answer is that your 401(k) plan doesn't need fixing, it needs a new record keeper. The Retirement Studio has a straightforward four-step process that converts your plan in approximately 90 days
DAYS 1-15Onboarding
We gather what we need to understand your current plan and company goals.
DAYS 15-35Plan Document Preparation
We prepare the documentation needed to establish your new plan structure.
DAYS 35-60Employee Enrollment
We guide your employees through enrollment, so no one is left behind in the transition.
DAYS 60-90Asset Transfer
We coordinate the transfer of existing assets, keeping the process smooth on both ends.
401(K) CALCULATORSee What Your Plan Could Look Like
Use our calculator to explore contribution scenarios and plan design options for your business.
PLAN SPONSOR QUESTIONSFrequently Asked Questions
-
A 401(k) advisor helps a business select and monitor plan investments, manage the relationship with the plan provider, keep the plan compliant, and educate employees, all while helping the company meet its fiduciary responsibilities under ERISA.
-
A 3(38) investment manager is a fiduciary who takes on legal responsibility for selecting and monitoring a retirement plan's investment lineup. This significantly reduces the plan sponsor's fiduciary liability compared to plans without one.
-
A 3(38) investment manager has full discretionary authority to select and monitor plan investments and carries the liability for those decisions. A 3(21) fiduciary only makes recommendations, leaving the final decision and the liability with the plan sponsor. The Retirement Studio serves as a 3(38) manager, which shifts more of that liability away from your business.
-
A CPFA® (Certified Plan Fiduciary Advisor) and an AIF® (Accredited Investment Fiduciary) are both credentials focused specifically on retirement plan fiduciary responsibility, covering plan governance, investment due diligence, and compliance. Our VP of Retirement Plan Services holds both, giving plan sponsors a dedicated point of contact with specialized fiduciary expertise.
-
A safe harbor plan is a plan design that automatically satisfies certain IRS nondiscrimination testing requirements, typically by providing a set employer contribution. It can simplify compliance for business owners, especially those with highly compensated employees.
-
Common designs include safe harbor, profit sharing, and cash balance plans, each suited to different goals and workforces. We help you evaluate which structure fits your company best.
-
Our streamlined process typically takes less than 90 days, covering onboarding, plan document preparation, employee enrollment, and asset transfer.
-
Costs vary based on plan size, design, and services needed. We provide clear, transparent fee structures upfront, so you know exactly what you're paying for before you commit.
WHO YOU’LL WORK WITHLed by Retirement Plan Specialists
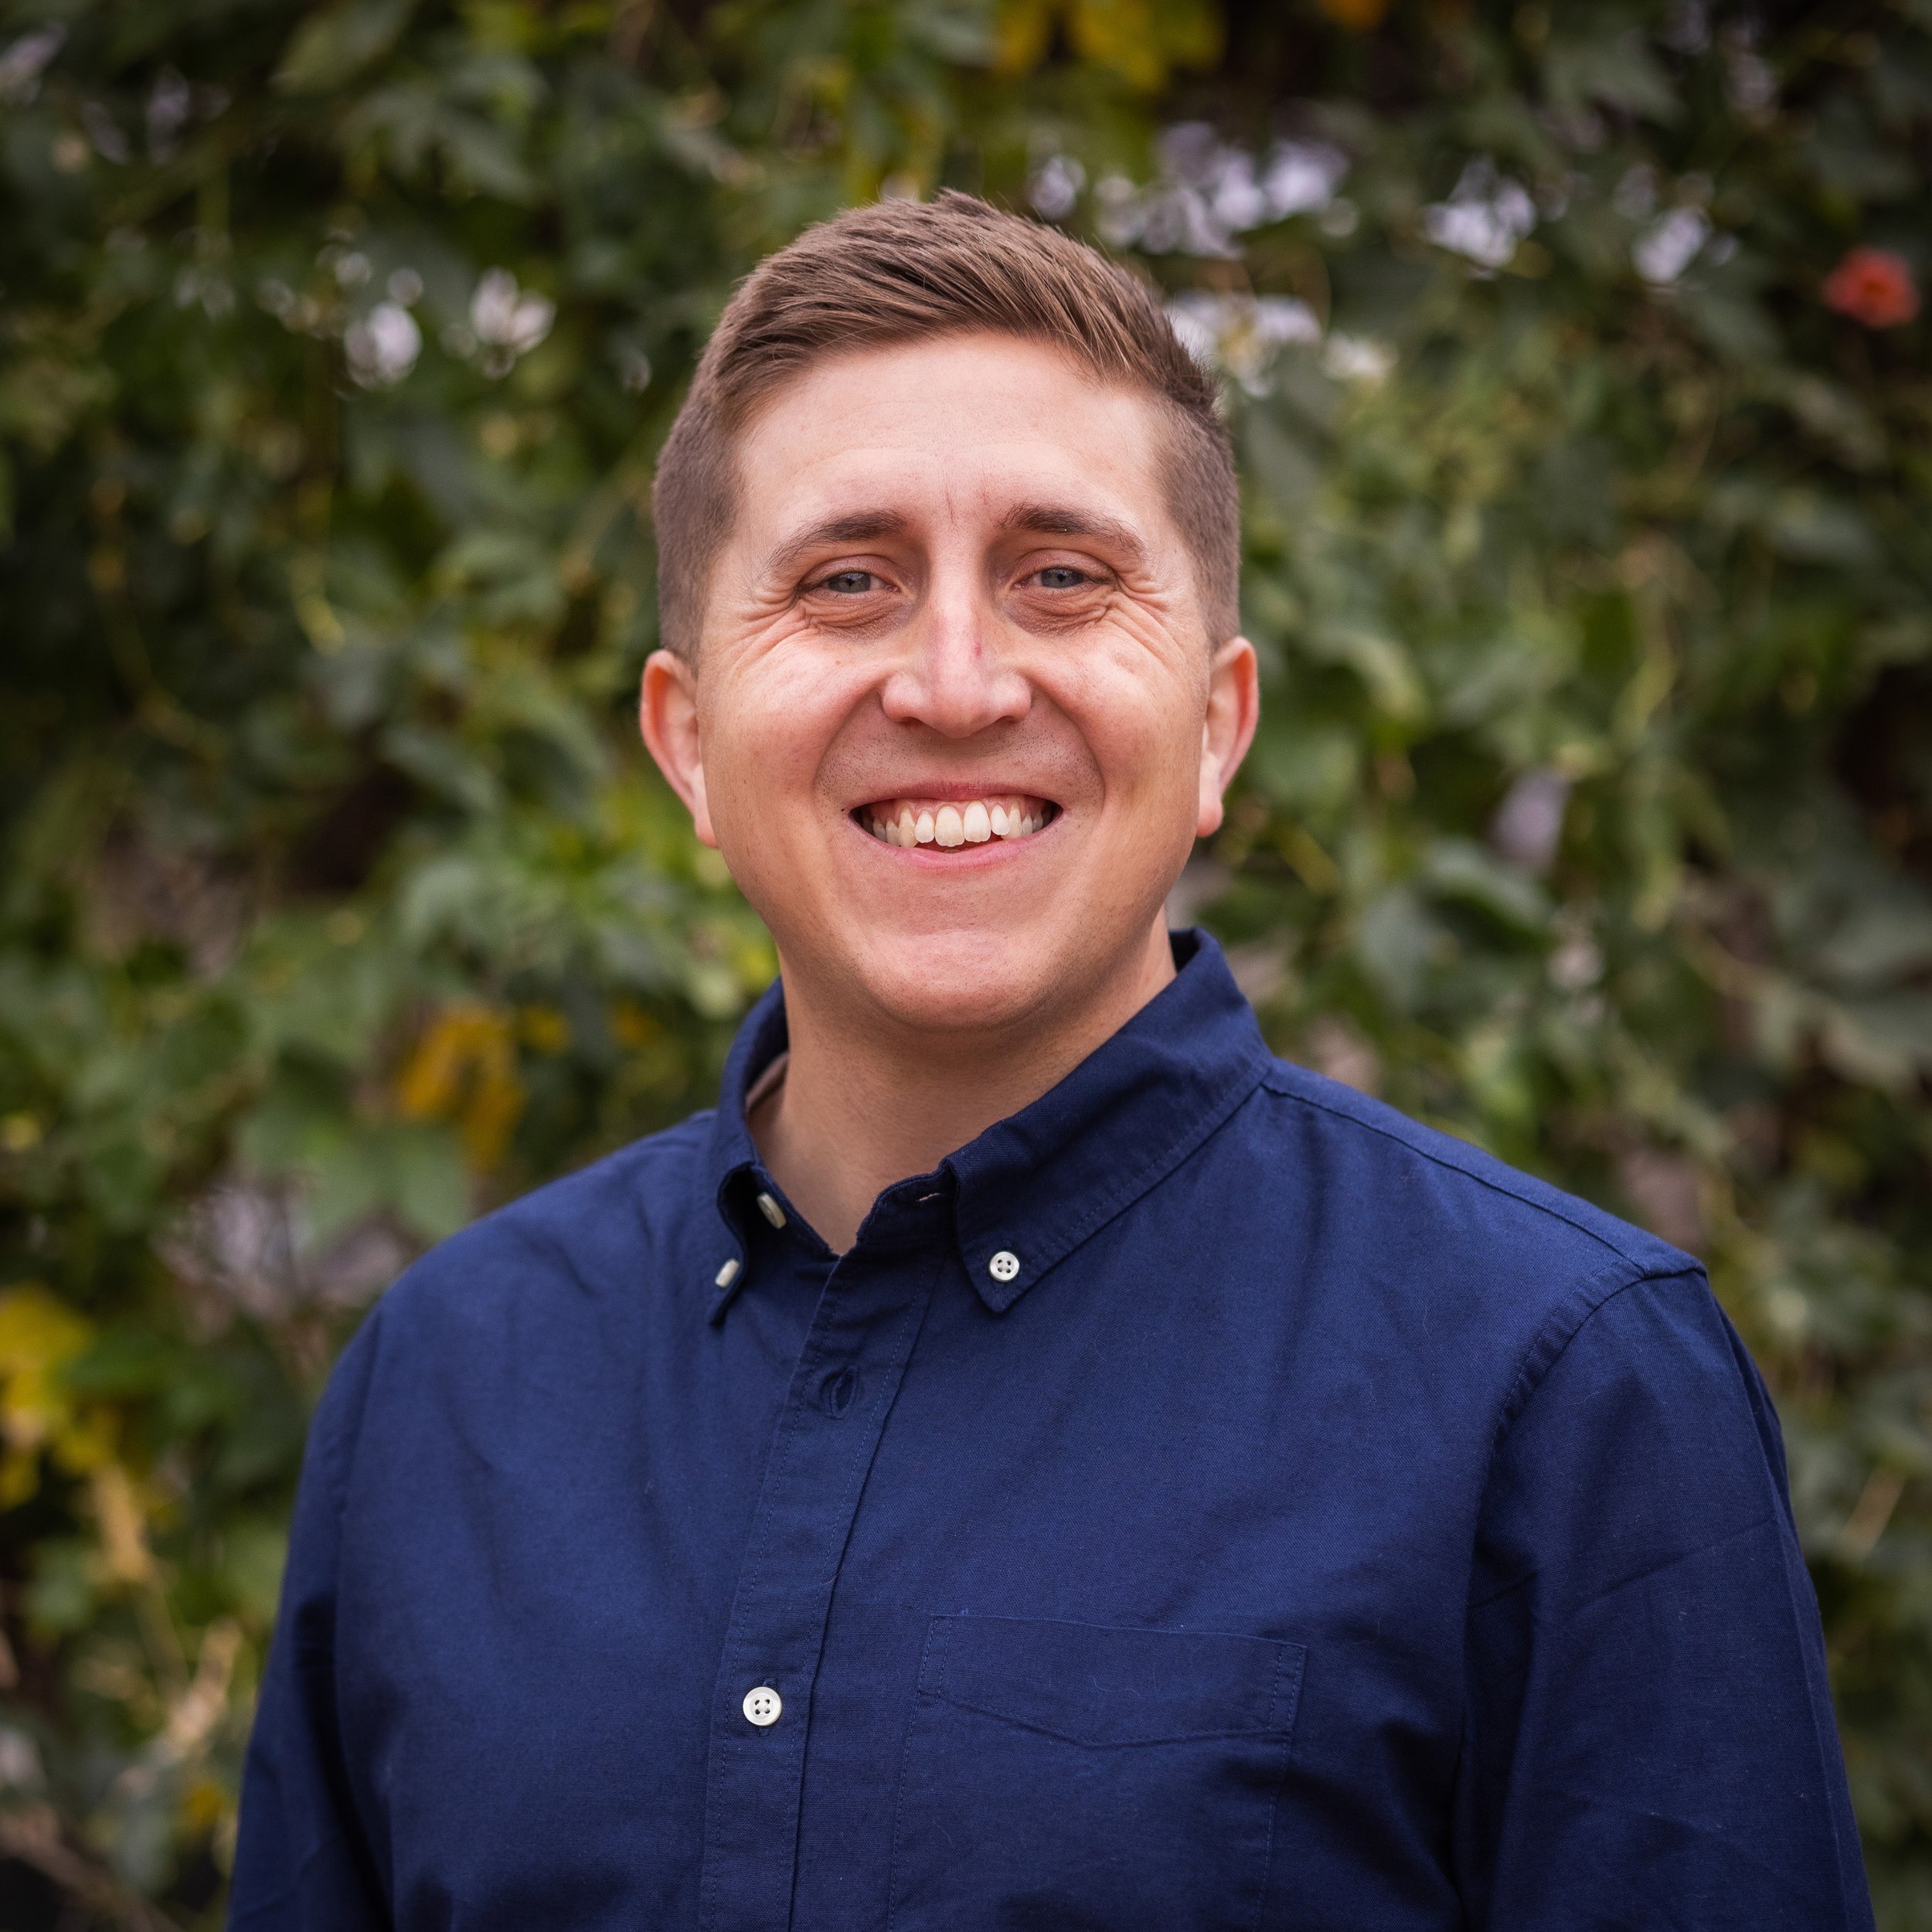
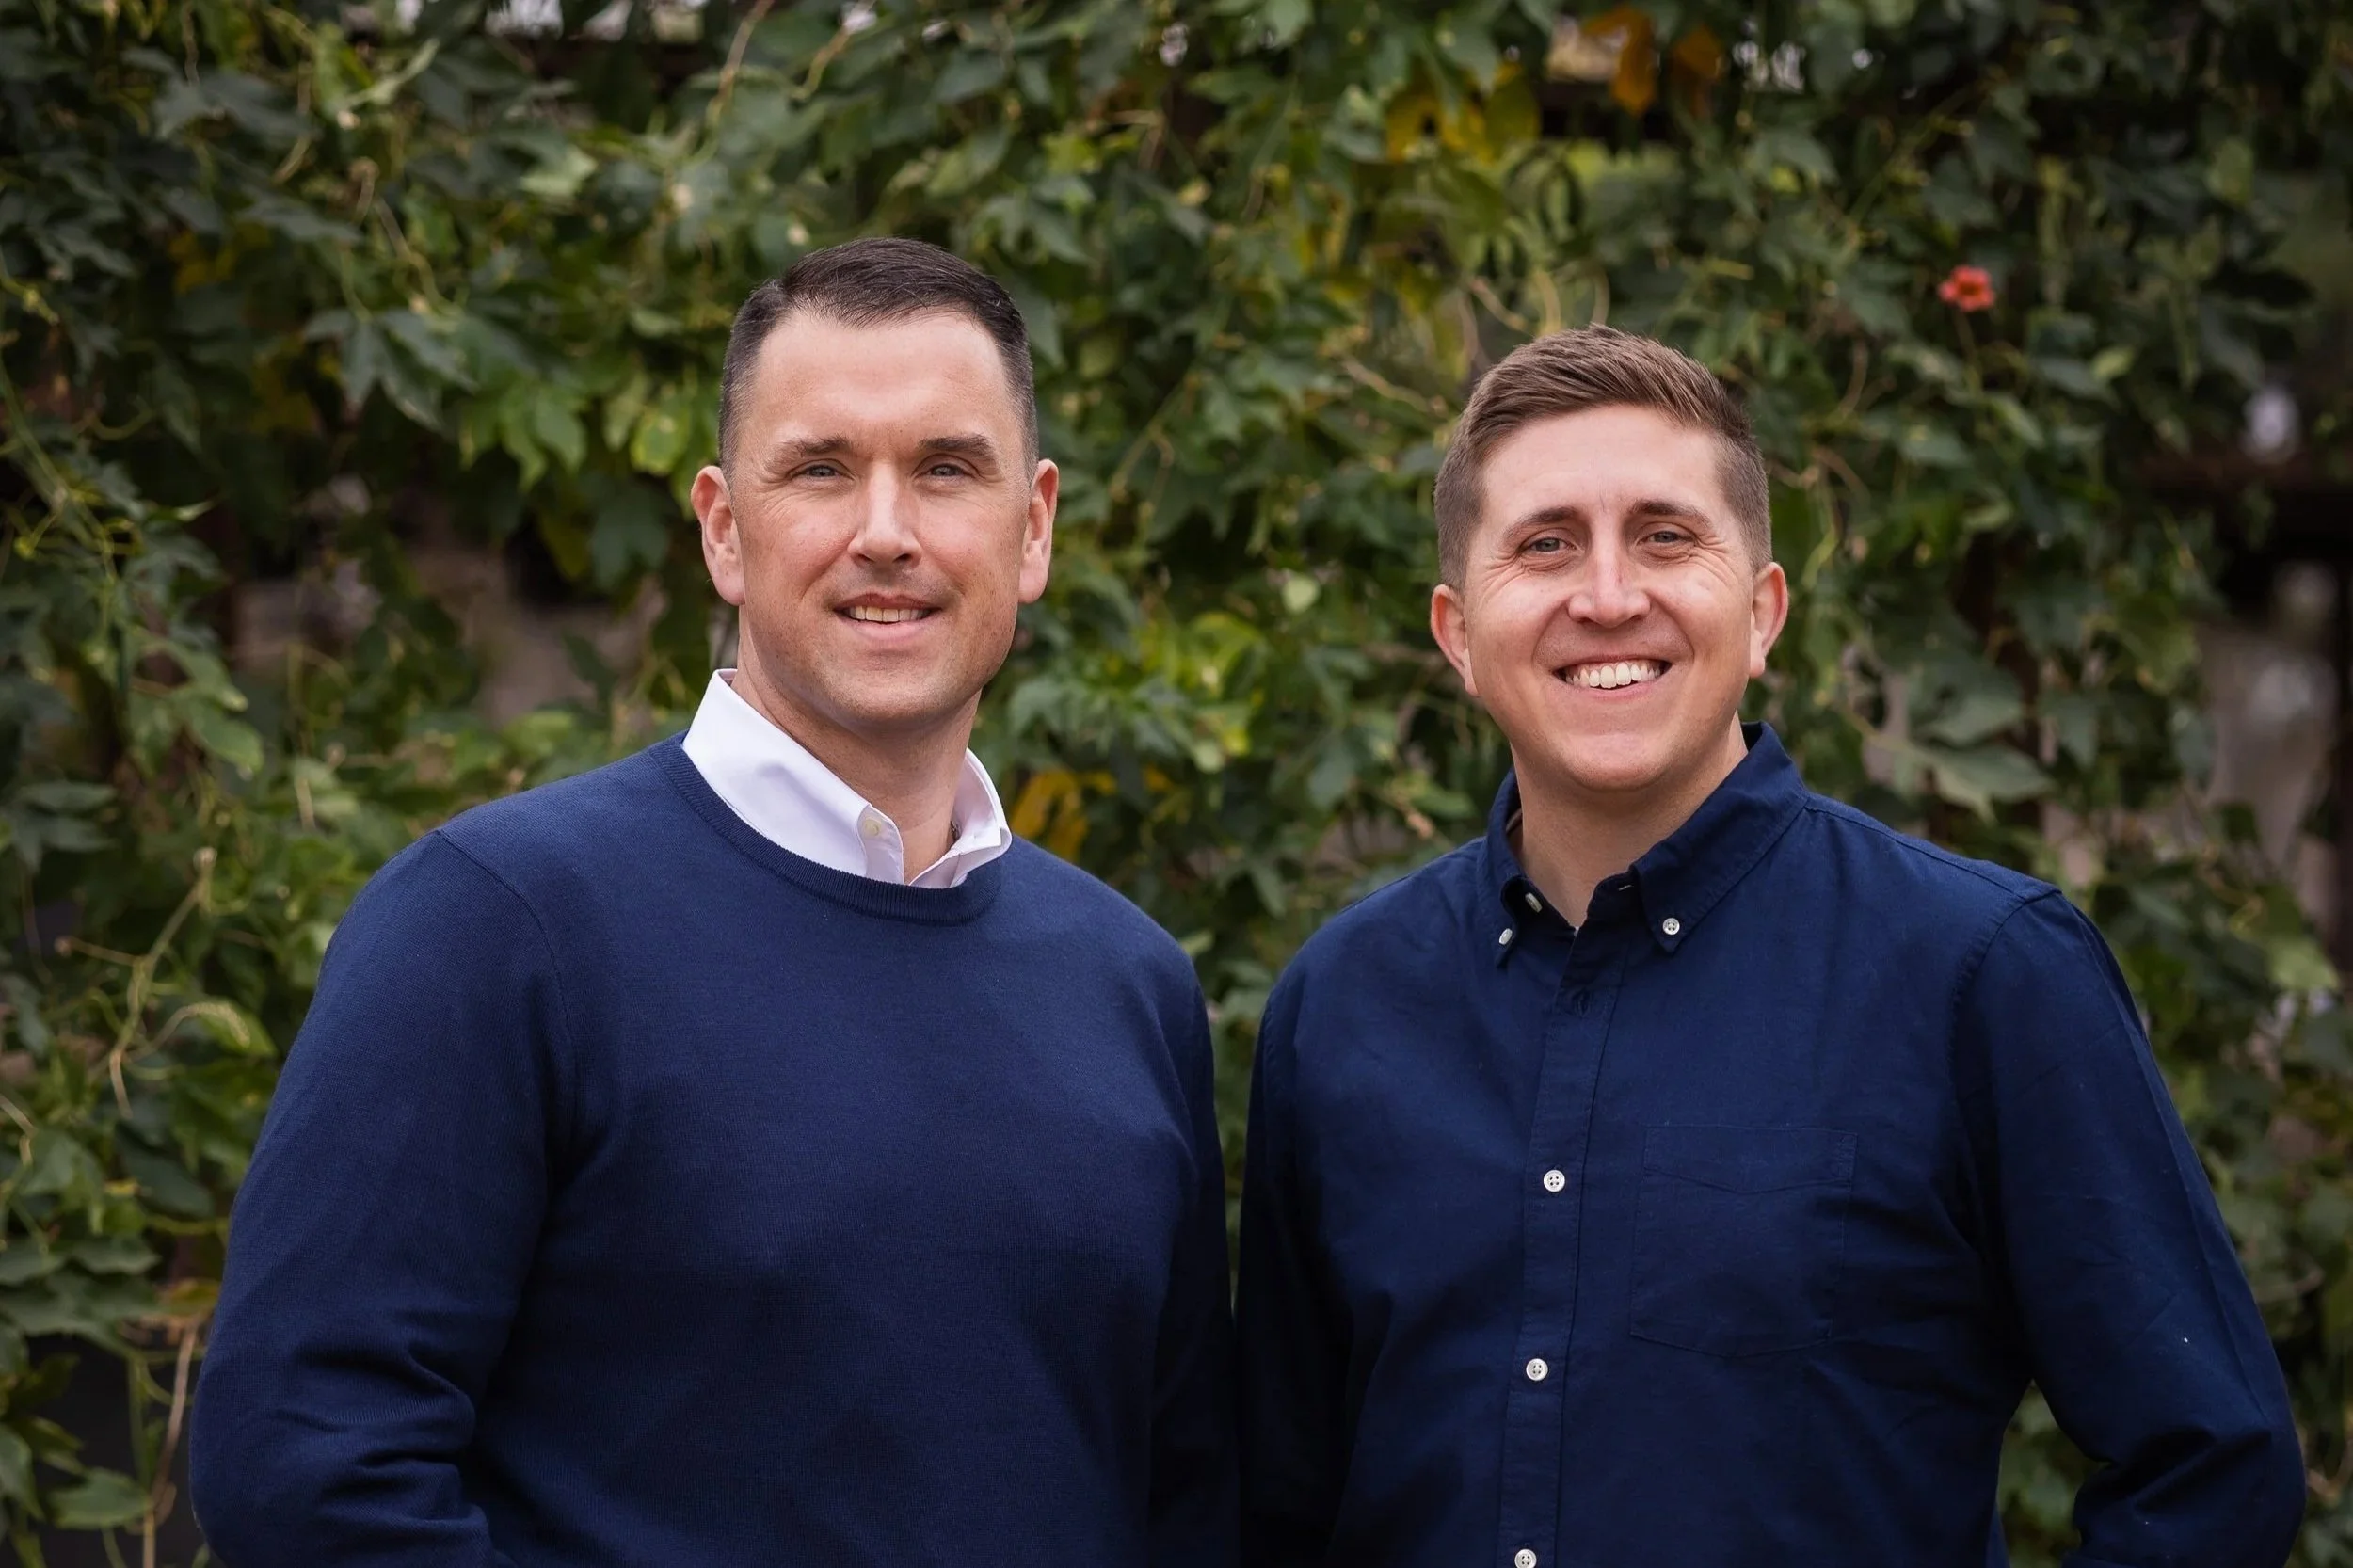
Brandon Barber
CO-FOUNDER & 401(K) SPECIALISTBrandon focuses on new business growth and plan design strategy, partnering with owners to build retirement plans that set their company and employees up for success.
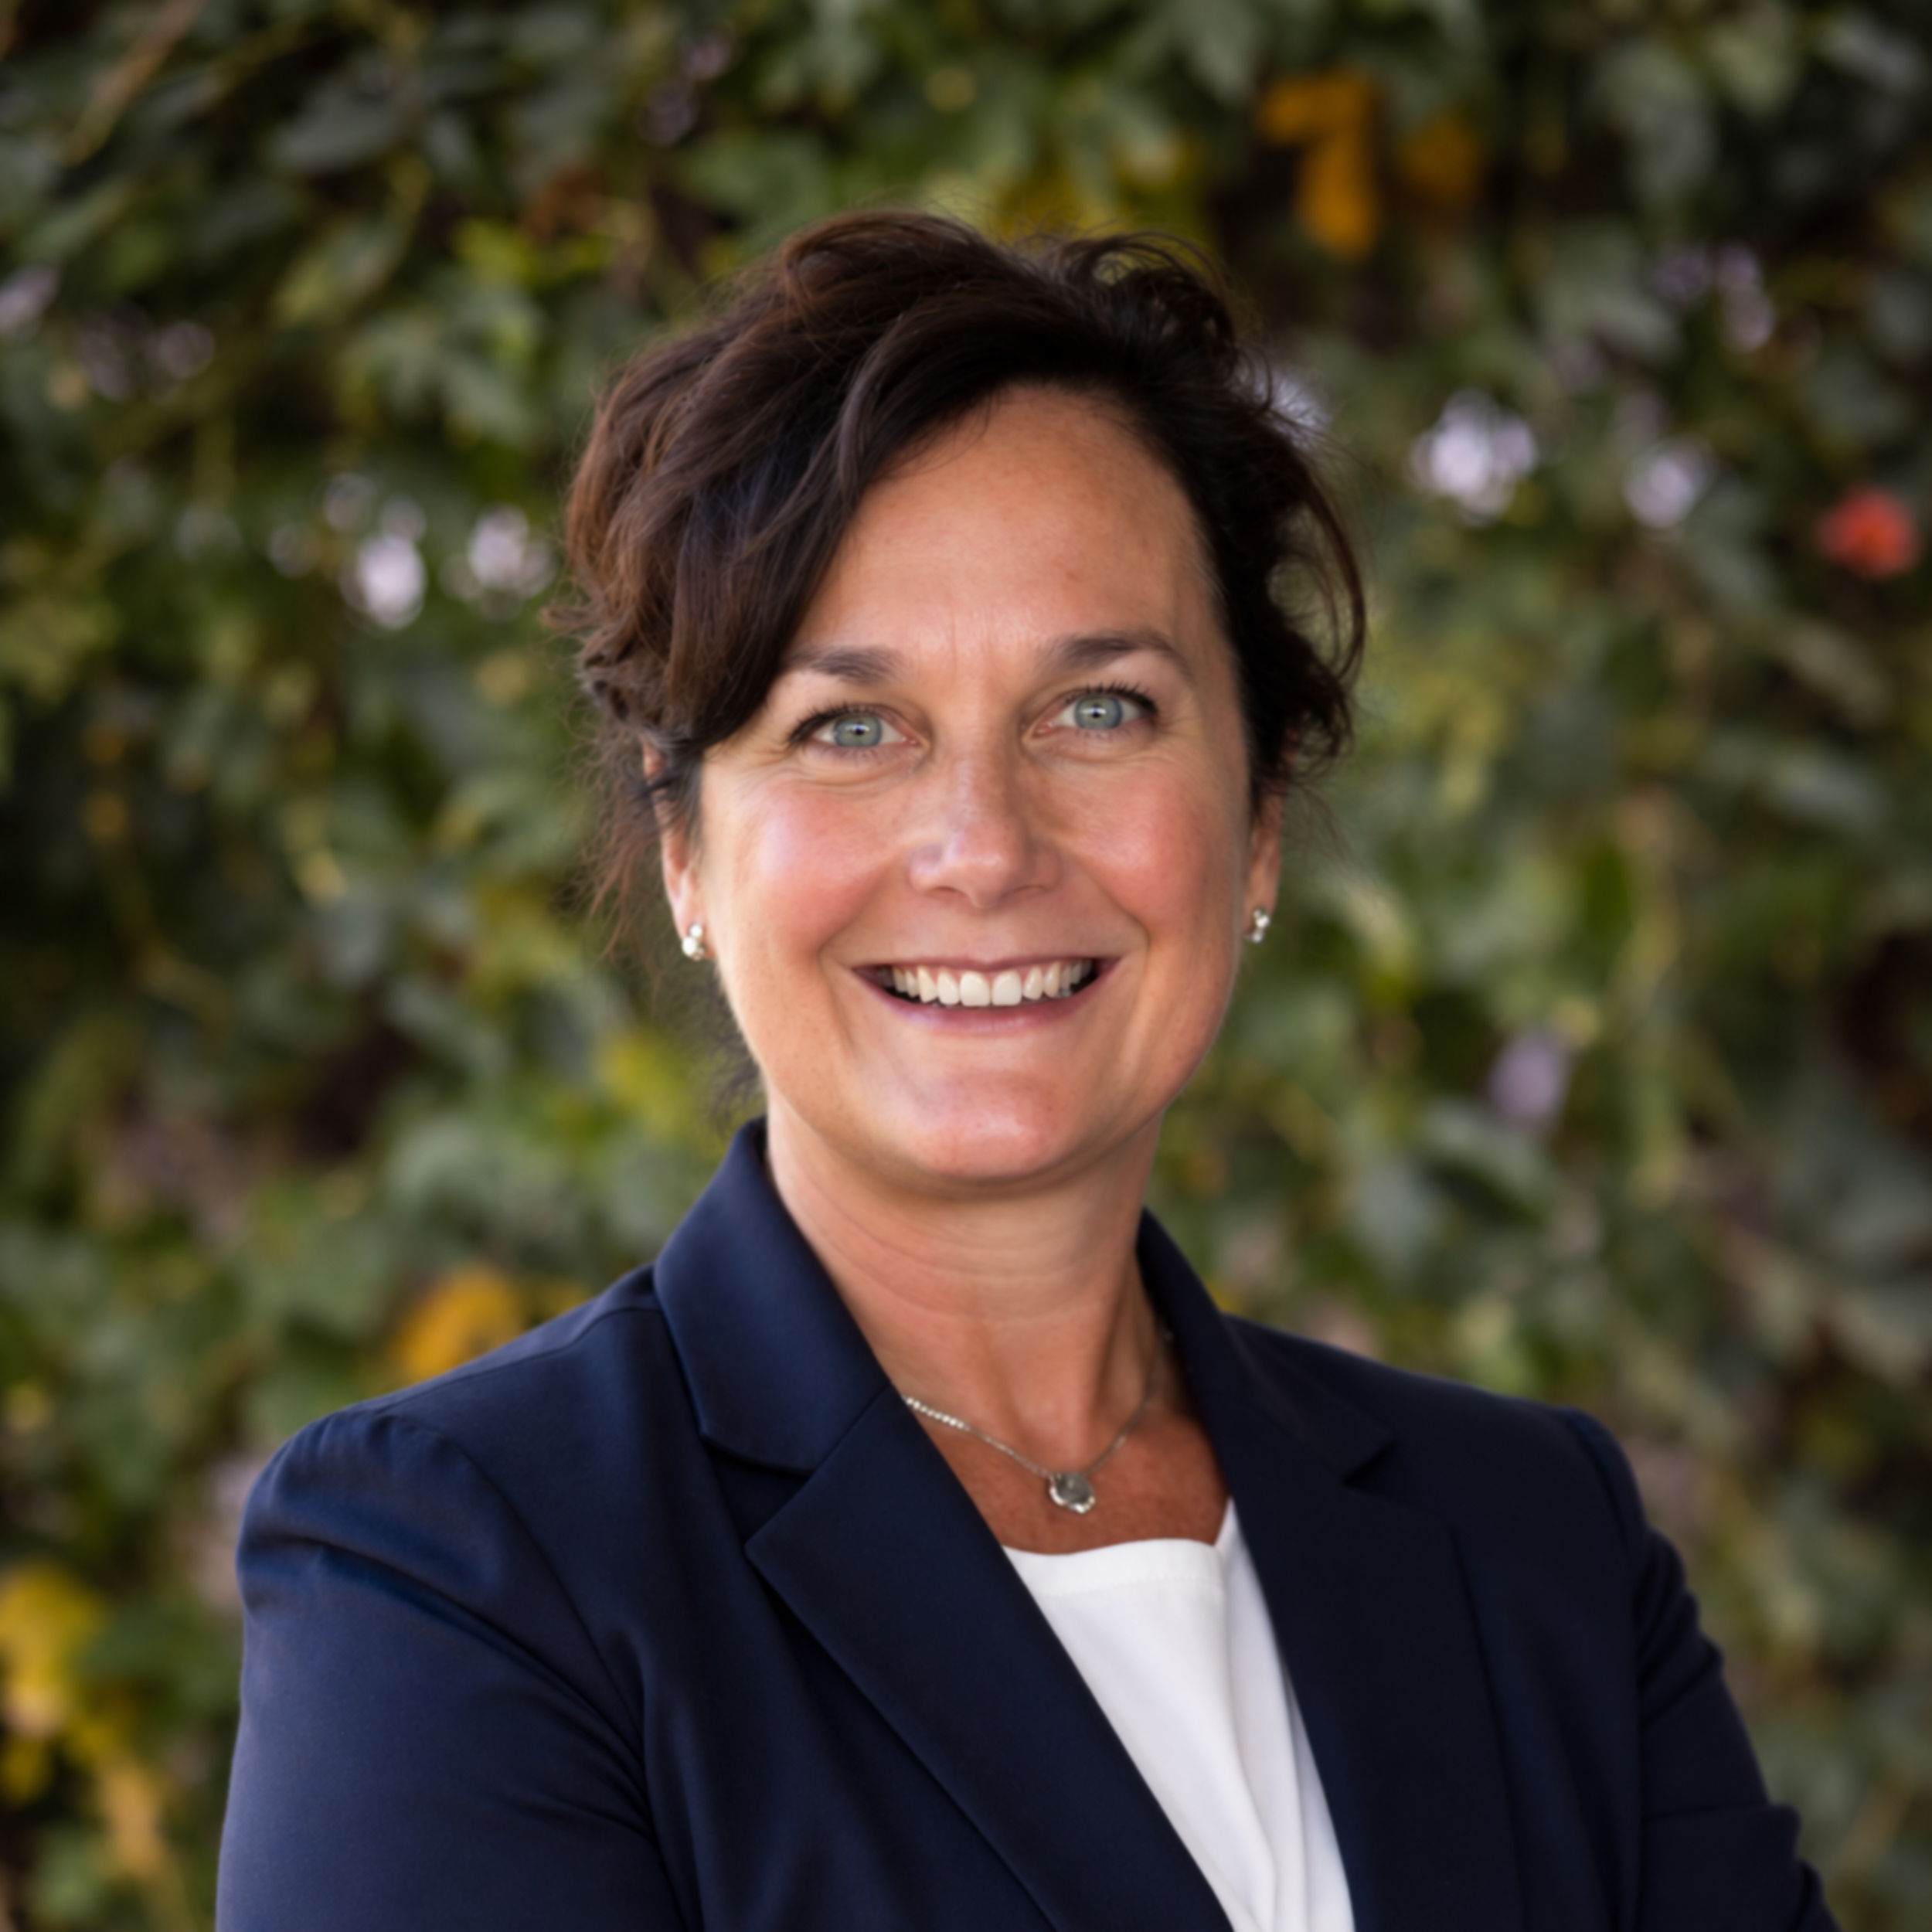
Kristin Dunlevy, CPFA®, AIF®
PLAN DESIGNKristin leads account management, quarterly reviews, plan compliance, and the ongoing work of improving outcomes for employers and employees.
STAY CURRENT401(k) Insights
Contribution limits, plan design strategy, and the practical work of building a benefit employees actually value.
BROWSE ALL INSIGHTS →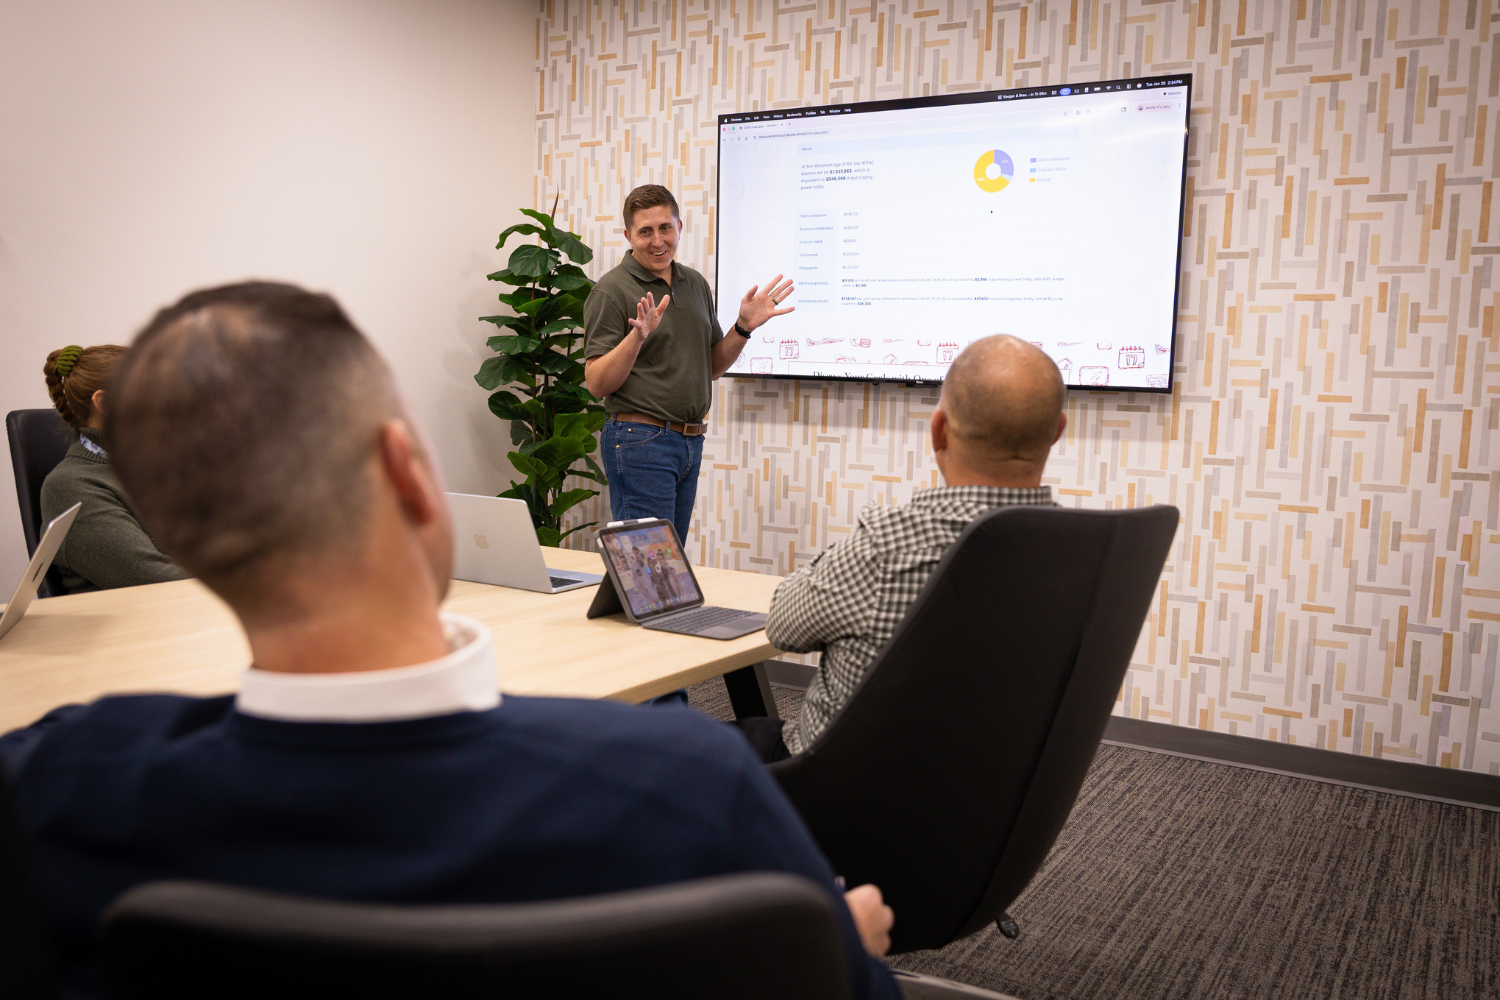
A BETTER BENEFIT STARTS HEREReady for a 401(k) Plan That Works Harder?
Let's talk about what a better plan could look like for your business and your team.